Construction costs, financing pressures and market uncertainty are making residential and living projects harder to deliver across every region we work in. In some markets, a significant proportion of approved projects aren’t progressing to construction as developers continue to grapple with rising costs and meaningful returns.
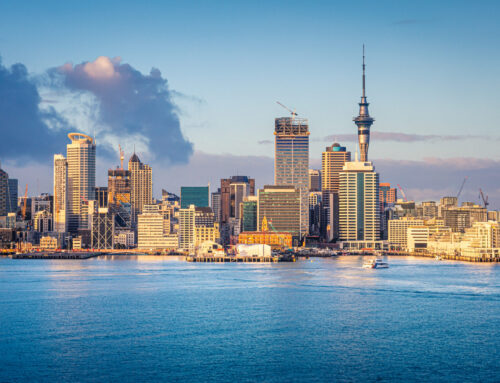
In Auckland, for example, declining apartment presales are contributing to project abandonments and prompting some developers to reconsider single-use schemes in favour of mixed-use models with different revenue streams.
Engineering can help respond to both challenges. At feasibility stage, a value-led engineering approach can test alternative systems, helping to reduce capital cost and program, protect flexibility and assess whether a different typology mix could be preferable. This gives developers better information on their return on investment before key design decisions are fixed.
Feasibility pressure across Australia, New Zealand, the UK and Canada
The causes of project abandonment vary by market but we’re seeing common pressures across regions. Construction costs are high, financing and presales are affecting viability and projects are being delayed, redesigned or pulled before construction.
| Market | Current feasibility picture | Construction cost pressure | Pipeline / delivery signal |
|---|---|---|---|
| Australia | Project feasibility remained challenging through 2025 and early 2026. Higher financing costs, labour constraints and cost volatility continue to affect whether approved projects proceed. | House construction costs are 51% above pre-COVID levels and rose a further 2% in Q2 2026. Higher-density costs rose 3.6% in 2025. | The National Housing Supply and Affordability Council says higher construction and financing costs are continuing to reduce project feasibility and may defer housing construction. |
| New Zealand | Residential building activity fell to a forecast NZ$26.1 bn in 2025, down from NZ$29.2 bn in 2024. | An elevated cost base for projects is the primary issue for projects. | The number of unsold saleable units in Auckland peaked in Q4 2025. This led to the highest number of project abandonments in the last 2 years during Q1 2026. |
| United Kingdom | Larger residential and multifamily development remains under pressure from higher financing costs, construction inflation and delays through the Building Safety Regulator process. | The Royal Institution of Chartered Surveyors respondents expect construction costs to rise 6.6% over the next 12 months, including 7.5% for materials. | The UK build-to-rent pipeline weakened through 2025 with construction volumes down 13% year-on-year in Q3, 29% lower in London. |
| Ireland | Development costs remain high, particularly for apartments. But, the current housing pipeline is improving. | Government continues to track total development cost across houses, apartments and student accommodation as viability remains a key issue. | 11,021 homes commenced in the first 4 months of 2026, up 176% year-on-year. This covers all housing types. Ireland is a useful counterpoint rather than a stalled-market example. |
| Canada | Housing starts rose 6% in 2025, driven by record rental construction. The market for apartments being developed for sale weakened. | Residential construction costs across 15 major metropolitan areas rose 2.3% year-on-year in Q2 2026. | The Canada Mortgage and Housing Corporation reports collapsed condominium (apartment) presales, rising unsold inventory and tighter finance. These are leading to project delays, cancellations and conversions to rental, particularly in Toronto and Vancouver. This is, in large part, due to an oversaturation in the market. |
Australia: residential feasibility pressure by state and territory
| State / territory | Higher-density construction cost escalation, 2025 | Evidence of projects not progressing |
|---|---|---|
| NSW | 3.6% | In metropolitan Sydney, 75% of apartments approved since 2020 had not progressed to construction. |
| VIC | 2.8% | Approved apartment and medium-density projects continue to face financial hurdles. |
| QLD | 6.4% | On the Gold Coast, around 60% of apartments due for completion in 2028–29 are considered at moderate or high risk of delay or withdrawal. |
| SA | 3.4% | Adelaide apartment feasibility remains constrained; public analysis points to a feasibility gap rather than a comparable stalled-project percentage. |
| WA | 5.5% | More than 12,500 apartments had been approved since 2020 but only around 2,140 had commenced construction. This means 83% hadn’t started. |
| TAS | 1.9% | Infrastructure and servicing constraints are a commonly cited barrier. |
| NT | 7.0% | No robust data available. |
| ACT | 0.5% | Dwelling commencements fell 57.4% in the December 2025 quarter. |
What can we learn from other markets?
This data shows that feasibility pressure doesn’t produce the same response in every market. Comparing regions can help project teams test local assumptions against approaches being used elsewhere.
- In Canada, record rental construction supported overall housing starts in 2025 while condominium presales weakened and some ownership projects were delayed, cancelled or converted to rental. This reinforces the value of testing tenure and operating models when market conditions change.
- Ireland provides a different comparison. Development costs remain a focus but housing commencements have recovered strongly.
- In the UK, financial constraints, planning and cost increases are affecting housing activity with a significant slowdown in the build-to-rent pipeline.
- Australia and New Zealand have their own combinations of construction cost, labour availability, infrastructure and market absorption.
The useful question at feasibility stage is whether comparable projects in other regions are solving the same problem differently. That may prompt a review of tenure mix, servicing strategy, procurement, standardisation, operational cost or the timing of key design decisions before those choices are fixed.
Bring value engineering into concept design
Value engineering is most useful when it’s brought in during the feasibility stage. If a project team knows which systems and specifications have reduced cost on comparable projects (and are a good fit for theirs), they can be brought forward into design development.
The building services’ team should aim to understand where CAPEX can help fulfill a project goal rather than try to cut cost by stripping back systems. Their goal should be to understand where expenditure contributes to the required project outcome and where a simpler solution may be suitable.
Maintain flexibility in the design
Decisions made during feasibility need to allow for flexibility later in the design process. If plant is located at roof, basement or intermediate levels, for example, this has different implications for riser space, servicing routes and future design changes.
Locating plant at roof level may require more riser space through the building but it can retain greater flexibility in how services are distributed. Intermediate or basement plant may reduce riser requirements but can firm up distribution strategies earlier. It’s important to understand what each option commits the project to before core and risers are fixed.
Flexibility can also support changes in the development’s typology mix. On some projects, developers are reconsidering the balance between build-to-sell residential, hotel, co-living and other uses as market conditions change.
Different typologies have different revenue models and some flexibility in the servicing strategy can be useful.
Consider program alongside capital cost
Taking an early contractor involvement (ECI) approach helps align design, procurement and construction planning. This creates opportunities to shorten the overall program and identify risks before they affect delivery.
The contractor can identify long-lead items and help the design team prioritise the information needed to progress those packages. This can allow procurement planning to begin while other parts of the design continue to develop.
Building services’ design needs to be closely coordinated with structure, facade and architecture. This is particularly important on refurbishment and adaptive reuse projects where conditions may only become fully understood once demolition or construction begins. Detailed coordination and a responsive project team can help resolve these issues quickly and reduce the risk of redesign delaying the program.
The same principle applies to authority engagement for utilities and fire safety. Power, water and fire life safety requirements should be tested early enough to confirm that the proposed servicing strategy is achievable.
Engineering helps you test your options
At feasibility stage, there’s often more than one technically-viable engineering solution. We always ask which building services’ option best supports the project’s commercial goals and operational requirements.
Different systems can have a significant impact on capital cost, plant space, maintenance requirements, energy use and occupant comfort.
On one mixed-use development in New Zealand, we compared 4 mechanical system options: 2 variable air volume (VAV) systems and 2 fan coil unit (FCU) systems. The VAV options used either electric reheat or heating hot water while the FCU options used either a 2-pipe chilled water system with electric reheat or a 4-pipe chilled and heating hot water system.
We then assessed each option against office grade, capital cost, plant area, riser space, maintenance, energy efficiency, acoustics, tenant flexibility and architectural impact.
Optioneering mechanical systems
| Mechanical option | Market positioning | Capital / spatial trade off | Operational trade off |
|---|---|---|---|
| VAV + electric reheat | A / Premium | Lower capital cost but larger risers reduce lettable area | Low tenant disruption due to centralised maintenance |
| VAV + heating hot water | A / Premium | Higher capital cost and larger risers | Better heating efficiency with some on-floor maintenance |
| 4-pipe FCU + heating hot water | A Grade | Smaller risers but highest system complexity | Highest maintenance burden and disruption risk |
| 2-pipe FCU + electric reheat | B Grade | Column 3 Value 4 | More maintenance within tenancies |
Our client’s preferred solution was neither the most expensive nor the cheapest. They chose the best balance between performance and cost for their development.
This type of comparison is useful because it avoids defaulting to the system most commonly used for a particular building type. Instead, the team can test several approaches to find the one that best suits the project.
Assess whole-of-life cost
We always look for the best commercial outcome rather than the lowest capital-cost as many assets will be owned and operated over the long term.
A lower-cost system may have higher maintenance requirements and greater energy use. Another option may cost more upfront but perform better over the life of the asset.
One way to assess this is to compare engineering options against project priorities. These could include capital cost, ease of maintenance, environmental performance, structural impact and other criteria.
This balance varies across residential apartments, hotels, build to rent, aged care, student accommodation, retirement living and co-living.
Understand where the market is heading
The right engineering solution depends on the product the project is trying to deliver and the market it will enter. Across living sectors, business models are evolving in different ways which changes the relative importance of capital cost, operational cost, flexibility, amenity and long-term performance.
The summary below relates to the Australian market.
Build to rent (BTR)
BTR has become an established asset class. Australia’s first generation of schemes is now reaching high occupancy and investors are gathering information on resident behaviour, operational cost and which amenities genuinely support retention and value.
This puts more scrutiny of whole-of-life cost, maintainability, energy use, resident experience and repeatable design. As the sector matures, there’s likely to be less appetite for amenity or systems that add capital cost without demonstrating a clear operational or rental benefit.
Co-living
Co-living is likely to continue developing as part of the broader response to affordability pressures and demand for professionally-managed rental accommodation. It also provides developers with another potential tenure model where conventional build-to-sell feasibility is difficult.
This places importance on efficient room planning, shared amenity, operational simplicity and services that can support higher occupancy densities. The challenge will be achieving enough amenity and value without allowing operating costs to undermine feasibility.
Hotels
Hotel performance is currently strong but new development is selective. Australian hotel supply growth is slowing due to construction costs, labour constraints and financing. At the same time, existing assets are benefiting from limited supply and strengthening demand. CBRE expects future supply to sit below both historical delivery and forecasted growth.
This could mean that new hotels will need a clear market position and disciplined cost base. Operational efficiency, room yield, maintenance access and energy use become particularly important because relatively small improvements multiplied across hundreds of rooms affect performance.
Residential apartments
Housing undersupply is expected to persist but this doesn’t make apartment development any more feasible. Rising building costs and financing constraints continue to restrict new supply while rental vacancy remains low.
This leads to greater pressure on efficient floorplates, plant and riser space, buildability and specification. Developers will choose features that support sales value to enable greater return. Flexibility to respond to changing apartment types, tenure or market positioning may also become more important.
Retirement living
Demand for retirement living is expected to grow as Australia’s population ages. One in 6 Australians is already aged 65 or over, with the 65+ population projected to double over the next 4 decades and the 85+ population expected to triple by 2065.
At the same time, residents are seeking greater independence, amenity and connection while operators need to manage the cost and complexity of increasingly sophisticated assets.
This is likely to place greater emphasis on adaptable homes, accessibility, ageing in place, lower running costs and services that can respond as residents’ needs change over time. Engineering decisions also need to support operational efficiency, maintainability and long-term resilience without making communities feel institutional.
Student accommodation
The underlying supply gap remains significant with CBRE estimating an unmet demand of around 185,000 purpose-built rooms, despite 34,000 beds projected to enter the market between 2026 and 2029.
This puts continued pressure to deliver beds efficiently while maintaining a product students are willing to pay a premium for. Standardisation, prefabrication, efficient layouts and durable systems have particular potential, balanced with communal spaces, security, pastoral support and student experience.
Make sure your building services team understands your priorities
When engaging your engineering team, be sure to gauge how curious they are. Your project partners should care about what you’re trying to achieve, who’ll be using the space they’re working on and how they can create the best possible design for your project.
This approach helps keep engineering decisions aligned with the project’s commercial requirements from feasibility through to delivery.
Commercial model
Communicate to your project team which of the following matter most to the project – capital cost, operational costs, program, yield, sustainability performance, market positioning, flexibility or a combination.
Target market
Who will buy, rent, stay in or operate the building? What level of performance and amenity is required?
Engineering options
Which systems have been tested; what are the cost and performance differences; and has the team considered alternatives to the standard approach?
Flexibility potential
Which choices around plant, risers, infrastructure and servicing should be resolved now and which should have flexibility built in?
Wider project impact
How do building services decisions affect structure, facade, utilities, procurement, program, maintenance and long-term operation?
Sources
NHSAC Quarterly Report – August 2026; NHSAC State of the Housing System 2026; Property Council / Urbis – NSW stalled apartment construction; Property Council / Urbis – Gold Coast Apartment Pipeline 2026; MBIE National Construction Pipeline Report; RICS UK Construction Monitor Q1 2026; Ireland – Insights into Total Development Costs 2025; Ireland – housing commencements, May 2026; Statistics Canada – Building Construction Price Index Q2 2026; CMHC Spring 2026 Housing Supply Report